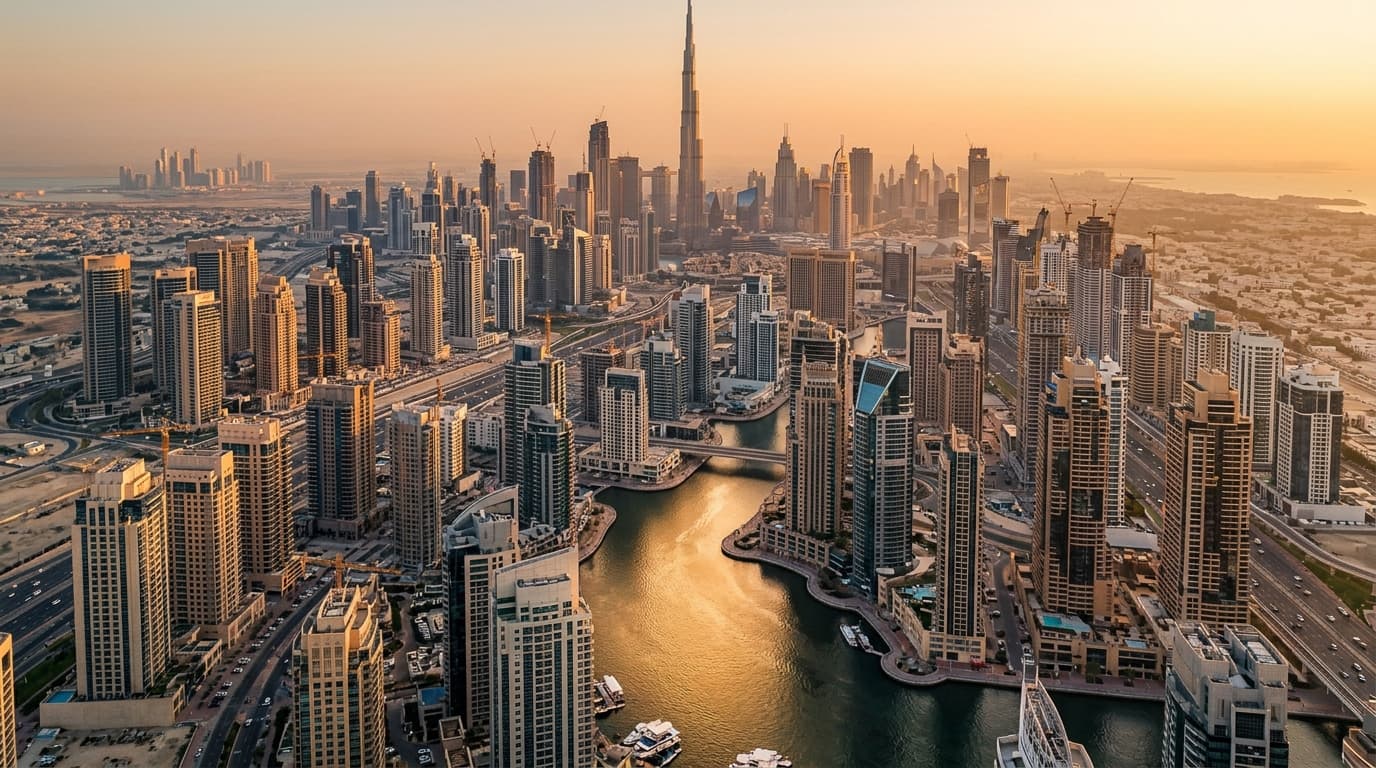
Regional headlines have been intense, yet Dubai’s property market continues to demonstrate resilience. A recent resident sentiment survey indicates that roughly 67% remain positive about Dubai real estate, citing the city’s stability, strong governance, and depth of lifestyle and employment options as key anchors.
This article unpacks how regional events have filtered through to demand, prices, and rents; why sentiment stays constructive; and what investors and end-users should do now to position wisely.
Sentiment Snapshot: Why Confidence Endures
Dubai’s safe-haven profile tends to strengthen when regional uncertainty rises. Three factors underpin the current 67% positive sentiment:
- Policy certainty: Clear rules on ownership, escrow-backed off-plan, and RERA oversight reassure buyers.
- Hard-currency peg: The AED’s peg to the USD reduces FX anxiety for global investors.
- Depth of demand: Population growth, business migration, and tourism continue to support both sales and rentals.
In practice, this has meant robust off-plan launches getting absorbed, continued end-user buying in well-connected mid-market communities, and prime segments retaining pricing power.
How Regional Events Channel Into Property Demand
Regional volatility typically re-routes capital toward perceived stability. In Dubai this manifests as:
- Safe-haven inflows: Investors from the wider Middle East, South Asia, and parts of Europe prioritize capital preservation via freehold assets in established communities.
- Family relocation: Parents prioritize schooling, healthcare, and connectivity; demand rises for villas and larger apartments in suburban hubs.
- Corporate moves: Company set-ups expand demand for executive rentals and central freehold stock.
These channels lift absorption in both ready and off-plan segments, often accelerating transactions in the mid-to-upper tiers where liquidity and exit options are strongest.
Sales Market: Off-Plan Resilience vs. Ready-Unit Urgency
Regional events have created a two-speed market:
- Off-plan: Developers leverage longer payment plans and phased pricing. Well-located launches by major developers tend to see strong day-one interest. Escrow protections and construction-linked schedules remain essential checks for buyers.
- Ready units: When uncertainty rises, some buyers prefer immediate handover. That urgency can tighten supply of quality ready stock in prime and near-prime zones, nudging prices.
Indicative pricing: Broadly, mainstream freehold apartments can range widely by community and specification, while prime waterfront or Downtown assets transact at materially higher AED per sq ft levels. Treat these as directional only; micro-location, views, and developer reputation drive dispersion.
Key costs to factor for buyers:
- Dubai Land Department (DLD) transfer fee: 4% of the purchase price
- Title deed and trustee office fees: typically a few thousand dirhams, varying by property type and trustee office
- Agency commission: commonly around 2% (negotiable)
- Mortgage registration: 0.25% of the loan amount (if financing)
Rental Market and Yields
Tight vacancy in popular communities keeps rents elevated, particularly for new, well-amenitized buildings and family villas. When regional uncertainty rises, some would-be buyers delay purchases and rent first, adding demand pressure to the leasing market.
Indicative gross yield ranges (not guarantees):
- Mainstream apartments: often around the mid- to high-single digits (illustratively 5%–8% depending on community and specification)
- Prime luxury apartments and villas: typically lower yields due to higher capital values (illustratively 3%–5%)
Holiday-home stock can see short-term volatility tied to tourism cycles; prudent operators price dynamically and maintain strong compliance with building and community rules.
Financing, Currencies, and the USD Peg
Mortgage costs in the UAE tend to move with USD-linked benchmarks. While rates have been higher than pre-2022 levels, serious end-users continue to transact, often with larger down payments to manage monthly outlay. Cash buyers remain an influential cohort, especially in prime and off-plan segments.
Currency effects matter: for buyers earning in stronger currencies, AED-pegged pricing can be attractive versus home-market volatility. For others, hedging or staged off-plan payments can smooth FX timing.
Policy Anchors That Support Confidence
Dubai’s regulatory framework is a key reason sentiment holds steady during regional events:
- Freehold ownership: Available to foreign buyers in designated freehold areas across Dubai.
- Escrow and RERA oversight: Off-plan payments flow into regulated escrow accounts tied to construction progress.
- Golden Visa via property: A 10-year residency is available for qualifying property investments from AED 2 million and above, subject to prevailing rules. End-users value the stability and family sponsorship options this offers.
- Transparent processes: Standardized MoU, NOC, and transfer at trustee offices, with digital services increasingly streamlining steps.
Supply Pipeline and Construction Costs
A visible pipeline of new communities and phases helps temper price spikes, but delivery timelines matter. Global materials costs and contractor capacity can shift build schedules, which in turn affects near-term supply in fast-absorbing sub-markets.
For investors, project due diligence should include contractor track record, handover history by the developer, and clarity on service charges post-completion.
Scenario Outlook: What Could Happen Next
- Baseline: Steady demand led by relocation and investment, moderate price growth in well-located communities, and firm rents due to population gains.
- Upside: Faster corporate migration or additional policy catalysts extend the cycle and tighten prime supply further.
- Downside: Prolonged higher global rates or external shocks could slow discretionary purchases and elongate selling periods in fringe locations. Well-priced, quality assets in core areas would likely remain more liquid.
Off-Plan vs Ready: How They Behave in Uncertain Times
| Factor | Off-Plan | Ready Property |
|---|---|---|
| Entry Ticket | Lower initial outlay via staged plans | Full price (or mortgage) at transfer |
| Flexibility | Payment timing can hedge FX/rate cycles | Immediate move-in/use; rental income starts sooner |
| Price Discovery | Launch pricing tiers and premiums vary by demand | Comparable sales easier to benchmark |
| Risk Profile | Construction and delivery timeline risk | Minimal development risk; building condition varies |
| Liquidity | Resale during construction depends on developer rules | Typically broader buyer pool for good stock |
Practical Steps for Buyers and Sellers Now
- Validate the developer: Escrow details, build history, and service-charge guidance.
- Stress-test financing: Model EIBOR-linked scenarios, fees, and post-handover payment plans.
- Compare micro-locations: Proximity to metro, schools, beaches, and job nodes can outweigh headline price.
- Price for today’s market: Sellers should track recent transfers, not just listings; buyers should factor total cost of ownership (service charges, maintenance).
- Document readiness: Title deed, service charge clearance, and NOC timelines can make or break a deal window.
Common Mistakes to Avoid
- Chasing the headline price only. Ignoring service charges, fit-out quality, and community liquidity can erode returns.
- Skipping escrow checks. Not verifying off-plan escrow and construction-linked schedules increases delivery risk.
- Underestimating transaction costs. Forgetting the 4% DLD fee, mortgage registration, and trustee fees skews budgets.
- Overleveraging at variable rates. Not stress-testing higher EIBOR scenarios can strain cash flow.
- Buying without a rental plan. Entering as an investor without a clear leasing or exit strategy risks vacancy and missed yield.
Conclusion
Regional events have reinforced Dubai’s role as a stable, well-regulated market, with resident sentiment holding constructive—roughly two-thirds remain positive. Safe-haven flows, policy clarity, and strong end-user demand underpin both off-plan absorption and ready-unit pricing. For investors and end-users, the edge lies in disciplined due diligence: verify developers, model total costs, and focus on micro-locations with enduring demand drivers.