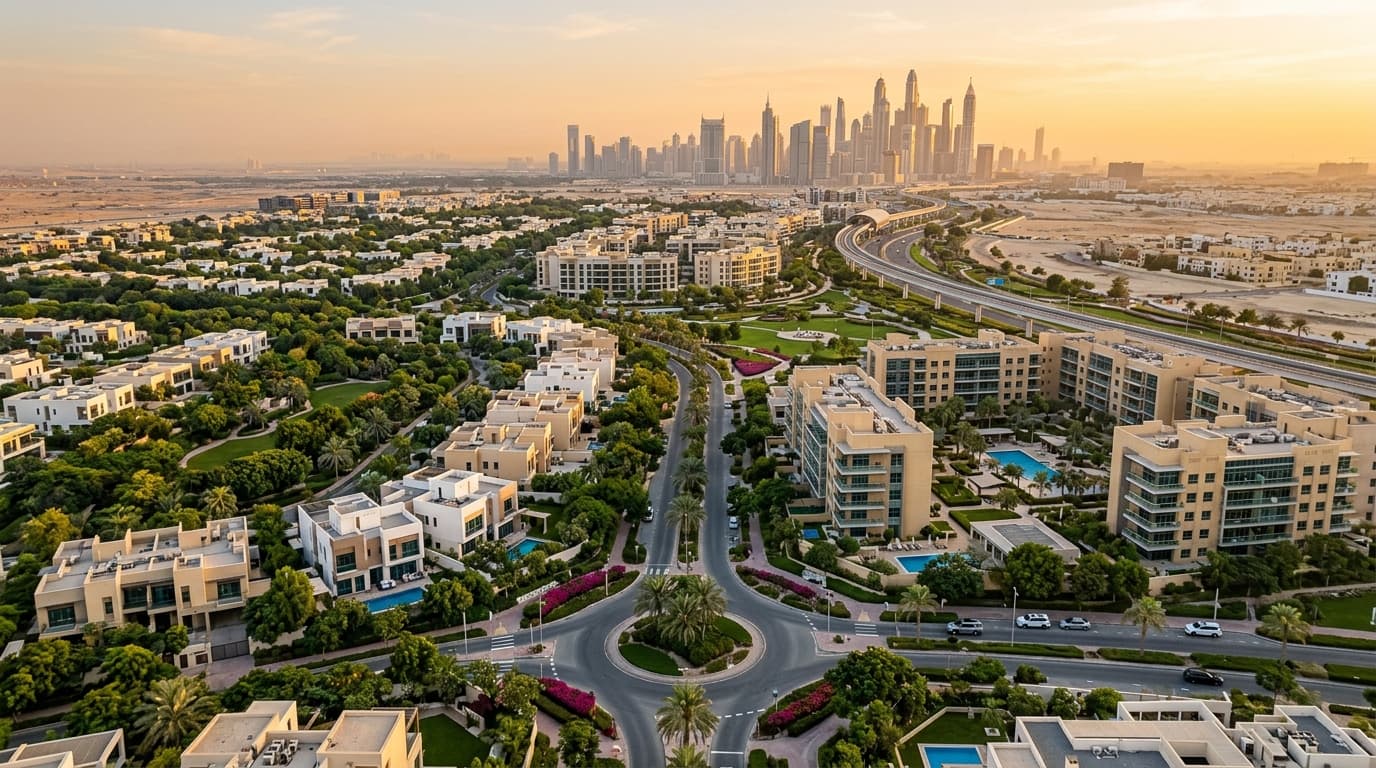
Al Furjan has matured into a firmly established freehold address in the Jebel Ali corridor, balancing family villas and townhouses with a growing stock of mid-rise apartments clustered around the Route 2020 Metro. As we move through September and October 2026, the community continues to benefit from strong connectivity, improving amenities, and steady end-user demand.
This update summarises what’s new on the ground, indicative pricing and yields, who’s transacting, and how Al Furjan stacks up for both investors and end‑users. Ranges cited are indicative based on prevailing market conversations and recent deal patterns rather than guarantees.
What’s new in Al Furjan (Sep–Oct 2026)
Al Furjan’s day-to-day liveability continues to improve as retail and fitness options at the Al Furjan Pavilions and Club remain community anchors. The Route 2020 Metro stations serving Al Furjan and Discovery Gardens keep apartment clusters especially attractive to commuters, while villa streets remain quiet and family‑oriented.
On the development front, handovers from several mid-rise apartment projects in and around Al Furjan’s eastern precincts have added to inventory, with additional completions expected in the coming quarters. Townhouse pockets on the western side have largely stabilised with limited new supply compared to the 2021–2024 wave, supporting price resilience.
Road access remains efficient via Sheikh Zayed Road and Sheikh Mohammed Bin Zayed Road corridors, with incremental junction and streetscape improvements easing peak-hour pressure. Retail vacancy at neighbourhood centres is comparatively low, and community services (nurseries, gyms, salons, clinics) have broadened.
- Steady apartment handovers near Metro nodes
- Tight resale supply for 3–4BR townhouses and 4–5BR villas
- Incremental streetscape and junction improvements
- Stable occupancy at Al Furjan Club and Pavilions
Sales market snapshot
Buyer demand remains two-speed: apartments benefit from affordability and Metro access, while landscaped townhouse/villa streets attract end-users trading up from neighboring communities. Cash buyers are active across both segments, with mortgage activity healthy, particularly for ready stock.
Indicative ready-sale ranges as observed in recent transactions:
- Apartments: 1BR and 2BR units commonly transact within an indicative AED 900–1,350 per sq ft band depending on age, finish, floor, and proximity to the Metro; brand-new handovers and larger 3BR layouts can stretch higher.
- Townhouses: Typical 3–4BR townhouses often see AED 1,050–1,450 per sq ft, with premiums for corner plots, landscaped outlooks, and recent handovers.
- Villas: Larger 4–6BR independent villas trade more on plot, layout, and renovation quality; per‑sq‑ft guidance is less linear but often sits in broad mid-to-high four figures per built-up sq ft for upgraded homes.
Off-plan: Select boutique launches continue, mostly low- to mid-rise apartments targeting mid-income buyers. Payment plans vary; investors should evaluate build track record, escrow compliance, and realistic completion timelines.
- Freehold ownership available to UAE nationals and expatriates
- DLD transfer fee: 4% of purchase price (plus admin/issuance fees)
- Mortgage buyers should allow for bank valuation variances
Rental market and yields
Al Furjan’s rental market remains occupancy‑driven, with metro-proximate apartments letting quickly, while family houses achieve longer tenures and lower churn.
Indicative annual rents (broad ranges reflecting building age, finishes, outlook, and access):
- Apartments: 1BR around AED 55k–85k; 2BR around AED 80k–130k; 3BR can extend beyond depending on size and spec.
- Townhouses: 3BR generally AED 180k–260k; 4BR AED 220k–320k; larger villas achieve higher figures, particularly if upgraded and landscaped.
Gross yields are typically stronger for apartments, often sitting in mid-to-high single digits in Al Furjan, with townhouses/villas usually in mid single digits depending on purchase price and maintenance profile. These are indicative ranges and not guarantees; net yields depend on service charges, vacancy, and financing costs.
- Apartments: faster letting cycles near Metro
- Houses: longer tenancy durations; consider maintenance budgeting
- Yield differentials hinge on service charges and capex needs
Who is buying and renting in 2026
End-user families remain the backbone of townhouse and villa demand, drawn by space, parking, and relative value versus more central villa districts. For apartments, a mix of first-time buyers, commuter professionals, and yield-focused investors are active, with interest from both UAE residents and international buyers seeking freehold entry points.
The AED 2 million Golden Visa threshold continues to motivate some buyers to consolidate into larger units or upgrade specifications to meet eligibility. Properties valued below that level remain popular for pure yield plays.
- End-user families dominate townhouse/villa segment
- Investors target Metro-adjacent apartments for yield
- Golden Visa planning influences some ticket sizes (AED 2M+)
Apartment vs Townhouse: which fits your strategy?
Use-cases and risk profiles differ between asset types. Apartments around the Metro nodes skew to liquidity and rental velocity, while townhouses reflect scarcity and end-user stickiness.
| Attribute | Apartments (Metro-proximate) | Townhouses/Villas |
|---|---|---|
| Typical buyer profile | Investor/first-time buyer | End-user/upgrader, long-hold investor |
| Entry price | Lower absolute ticket sizes | Higher ticket, limited new supply |
| Indicative gross yields | Mid-to-high single digits | Mid single digits |
| Letting speed | Generally fast | Slower but longer tenures |
| Key risks | Service charges, building competition | Maintenance capex, liquidity cycles |
| Value drivers | Walkability, building quality, views | Plot, layout, upgrades, community pocket |
Practical due diligence checklist
- Verify service charge schedules and any planned increases; factor them into net yield.
- For apartments, review building snag history, chiller arrangements, and owners association health.
- For houses, inspect waterproofing, AC, and landscaping irrigation; review any extension approvals.
- Confirm parking allocations and visitor parking realities, especially near busy nodes.
- If financing, obtain an AIP (approval in principle) and plan for valuation gaps.
- Budget for the Dubai Land Department’s 4% transfer fee, trustee office fees, and any developer NOC charges.
- For off-plan, confirm escrow compliance, payment milestones, and long-stop dates.
Regulatory and ownership notes
Al Furjan is a designated freehold area where UAE nationals and expatriates can acquire full ownership. Standard Dubai processes apply:
- Buyers pay the 4% Dubai Land Department transfer fee plus registration/admin fees.
- Title is registered via an approved trustee office; off-plan units are recorded in the Oqood system until completion.
- Foreign buyers seeking residency through property should note the property-linked Golden Visa generally requires a minimum AED 2 million property value and meeting other eligibility criteria at the time of application.
Timelines, fees, and criteria are subject to change; always confirm the latest with the relevant authorities and your advisor.
Outlook for the next 6–12 months
The supply picture in Al Furjan points to a moderate pipeline of apartments relative to constrained new townhouse/villa stock. This typically supports price stability for quality family homes, while apartment performance will hinge on building quality, Metro proximity, and service cost competitiveness.
Investors should expect a continued focus on ready units for immediate rental income, with selective off‑plan opportunities where pricing, payment plans, and developer track record align. End-users may find negotiation room on older stock requiring upgrades, offset by premiums for turnkey, well-located homes.
- Apartment pricing to bifurcate by quality and location
- Townhouse/villa scarcity underpins values in popular pockets
- Yield resilience linked to service charges and tenant retention
Common Mistakes to Avoid
- Ignoring service charges. Overlooking annual charges can erode net yield even when gross numbers look attractive.
- Underestimating maintenance for houses. Townhouses and villas require ongoing AC, waterproofing, and landscaping budgets.
- Chasing the cheapest off-plan. Prioritise developer track record, escrow compliance, and realistic timelines over headline pricing.
- Skipping a bank valuation check. Financing without an AIP or valuation guidance can create last‑minute shortfalls.
- Bidding without Metro awareness. In apartments, distance to the station materially affects rentability and resale.
Conclusion
Al Furjan’s blend of Metro-linked apartments and family-friendly houses continues to appeal to both investors and end-users in late 2026. With steady handovers, robust amenity coverage, and constrained new townhouse supply, the community offers balanced opportunities. Focus on micro-location, building quality, and total cost of ownership to make a resilient decision in the months ahead.