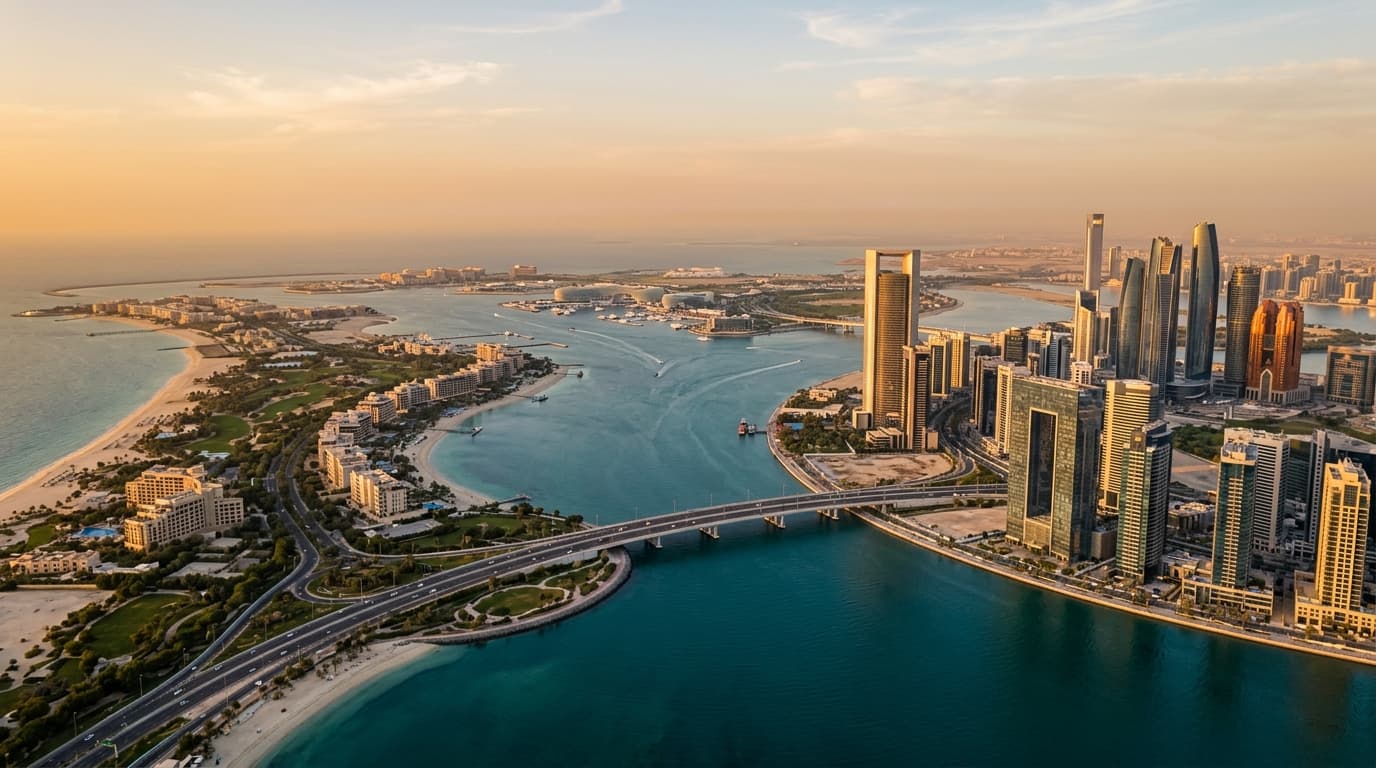
Abu Dhabi’s sales market in Q3 continued to show resilient end-user demand alongside strong off-plan absorption in prime waterfront and lifestyle districts. Villas and townhouses remained supply-constrained, while well-located apartments with good amenities saw steady transaction activity supported by realistic pricing and flexible developer plans.
This report distils what moved in Q3, where buyers found value, how off-plan compared to ready stock, and the practical costs and timelines that buyers should budget for in Abu Dhabi.
Q3 at a glance: what moved the market
Buyer enquiries in Q3 were concentrated in waterfront lifestyle hubs (Saadiyat Island, Yas Island, Al Raha Beach) and established apartment districts (Al Reem Island). Off-plan launches with staged payment plans captured investors seeking capital appreciation and lower entry tickets, while ready villas with practical layouts and proximity to schools remained competitive and often transacted quickly.
Typical vendor expectations moderated where listings were abundant, but limited quality villa stock maintained firm pricing. Mortgage-backed purchases were active, with many buyers optimising loan-to-value (LTV) within Central Bank guidelines and negotiating minor price adjustments or closing-cost support rather than headline discounts.
- Waterfront and family communities led absorption.
- Off-plan drew investors; ready stock attracted end-users.
- Villas remained tight on supply; well-priced apartments moved steadily.
Price and yield snapshot by community
The following ranges are indicative Q3 resale/ready benchmarks; individual assets vary by view, floor, finish, developer reputation, and payment flexibility.
| Community | Apartment price range (AED/sqft) | Villa/Townhouse ticket (AED) | Gross yield (typical) |
|---|---|---|---|
| Al Reem Island | 900 – 1,400 | N/A | 6.0% – 7.5% |
| Yas Island | 1,200 – 1,900 | 2.8M – 6.5M+ | 5.0% – 6.5% |
| Saadiyat Island | 1,600 – 2,600 | 6.5M – 20M+ | 4.0% – 5.5% |
| Al Raha Beach | 1,100 – 1,700 | 3.5M – 8.5M+ | 5.0% – 6.5% |
| Khalifa City/Al Forsan area | N/A | 4.0M – 10M+ | 4.5% – 5.5% |
These are not guarantees and should be stress-tested via recent comparables, service charges, and achievable rents for each unit type.
Off-plan vs ready: Q3 performance and trade-offs
Off-plan: Developers in prime districts leveraged phased payments and post-handover options, attracting buyers seeking lower upfront costs and potential appreciation before completion. Early-phase pricing and premium views/floor plans were bid most competitively.
Ready: End-users favoured turnkey units in buildings with strong occupancy, proven facilities, and transparent service charges. Villas with usable gardens and proximity to schools and retail saw short marketing periods when priced within recent comps.
Key considerations:
- Off-plan: construction and handover timelines, developer track record, escrow-backed structures, and resale restrictions.
- Ready: immediate transfer costs, renovation budgets, and bank valuation versus agreed price.
- Off-plan offered flexible payments; selection matters early in a release.
- Ready stock provided immediate use and clearer yield visibility.
Villas, townhouses, and apartments: demand patterns
Villas and townhouses: Family-led demand and limited new handovers supported prices across Yas, Saadiyat, and established suburban nodes. Practical floorplans, shaded outdoor space, and proximity to schools were consistent priorities.
Apartments: Waterfront and integrated community living remained the theme. Buildings with strong management, efficient layouts, and covered parking sustained absorption, while older stock without upgrades competed on price.
Studio and 1-bed units in employment-proximate locations continued to anchor investor interest given their liquidity and rentability.
Mortgage and finance conditions buyers navigated in Q3
Most banks in the UAE follow Central Bank LTV caps. For many non-UAE national buyers, maximum LTV on a first ready home typically reaches up to 80% (subject to eligibility and bank policy). For off-plan purchases, practical LTVs are lower, commonly around 50%, with disbursements tied to construction milestones. Mortgage rates and fees vary by lender and profile.
Practical tips:
- Obtain an approval-in-principle before serious viewings to anchor budget and timelines.
- Allow for bank valuation variances; if a valuation prints below the agreed price, top-up cash may be needed.
- Consider total cost of credit: rate, processing fee, life/property insurance, and early settlement terms.
- Typical first-home LTV for non-UAE nationals up to 80% on ready stock (subject to bank).
- Off-plan finance often caps lower with milestone-linked disbursements.
Fees and timelines: Abu Dhabi resale workflow
Abu Dhabi transactions are registered with the Department of Municipalities and Transport (DMT). In designated investment zones, foreign buyers can purchase freehold or long-term interests in line with local regulations.
Typical resale steps:
- Offer and Memorandum of Understanding (MoU) agreed; deposit terms defined.
- If mortgaged, buyer secures approval-in-principle; bank orders valuation.
- Developer/Community clearances and No-Objection Certificates (NOC) obtained; settlement statement issued.
- Transfer appointment completed via DMT/TAMM; title issued digitally.
Indicative buyer costs in Abu Dhabi (subject to change and individual deal terms):
- DMT registration fee: typically 2% of the purchase price.
- Agency fee: commonly around 2% (plus VAT where applicable), negotiable case-by-case.
- Admin/NOC/developer fees: vary by project and can range from a few hundred to several thousand dirhams.
- Mortgage-related costs (if applicable): bank processing fee, valuation fee, property insurance, and life insurance.
Typical timeline from MoU to transfer ranges from 2–6 weeks for cash deals; mortgage cases can extend depending on bank and valuation.
Rental market interplay and gross yields
Rising occupancy in prime lifestyle areas supported stable to firm rents in Q3, underpinning yields for investment-grade apartments. Villas saw steady leasing demand from families prioritising school catchments and space.
Gross yields in central apartment districts typically pencilled in the mid-5% to high-6% range, with compact units near employment hubs often at the upper end. Prime beachfront stock traded at lower yields reflecting capital preservation and lifestyle value. Net yields depend on service charges, community fees, and maintenance assumptions.
- Compact units near job hubs: higher gross yield potential.
- Prime waterfront: lower yield, stronger end-user appeal.
Service charges and running costs to benchmark
Service charges in Abu Dhabi vary by asset class and amenity load. As a broad indication:
- Apartments: many buildings range around AED 10–20 per sq ft per annum, with premium towers potentially higher due to facilities.
- Villas/Townhouses: often assessed on plot or built-up area, with lighter shared facilities yielding lower per-sqft figures than full-service towers.
Review recent service charge statements, sinking fund provisions, and maintenance history when calculating net yield. Adjust for chiller, parking, and any community club charges.
Q4 outlook and strategic positioning
With steady demand in family-centric and waterfront districts, we expect Q4 to continue rewarding realistic sellers and committed buyers. Off-plan phases in well-located master plans should attract reservation interest, while ready stock priced in line with bank valuations will clear.
Strategies to consider:
- Investors: prioritise buildings with robust occupancy, competitive service charges, and efficient layouts; target units with immediate rentability.
- End-users: focus on community fundamentals—schools, commute, retail—then weigh total cost of ownership versus headline price.
- Sellers: pre-empt buyer due diligence with updated service charge statements, snag/maintenance receipts, and a clean mortgage liability letter where relevant.
- Price to recent comps and bank valuation bands to maintain deal momentum.
- Lean on flexible completion dates to accommodate mortgage processes.
Common Mistakes to Avoid
- Ignoring total purchase costs. Not budgeting for the 2% DMT fee, agency, NOC, and mortgage expenses can derail completion.
- Chasing headline yield only. Overlooking service charges, vacancy risk, and realistic rent can compress net returns.
- Skipping bank pre-approval. Viewing before financing is aligned often leads to missed opportunities and renegotiations.
- Overvaluing unproven off-plan. Not assessing developer track record, escrow protections, and exit restrictions adds risk.
- Neglecting valuation risk. Agreeing a price far above recent comps can require unexpected cash top-ups if the bank values lower.
Conclusion
Q3 reaffirmed Abu Dhabi’s twin-engine market: lifestyle-led end-user demand in prime districts and steady investor interest for well-priced, rent-ready apartments. With clear visibility on fees, timelines, and finance, buyers can execute confidently, while realistic, documentation-ready sellers will continue to capture liquidity into Q4.