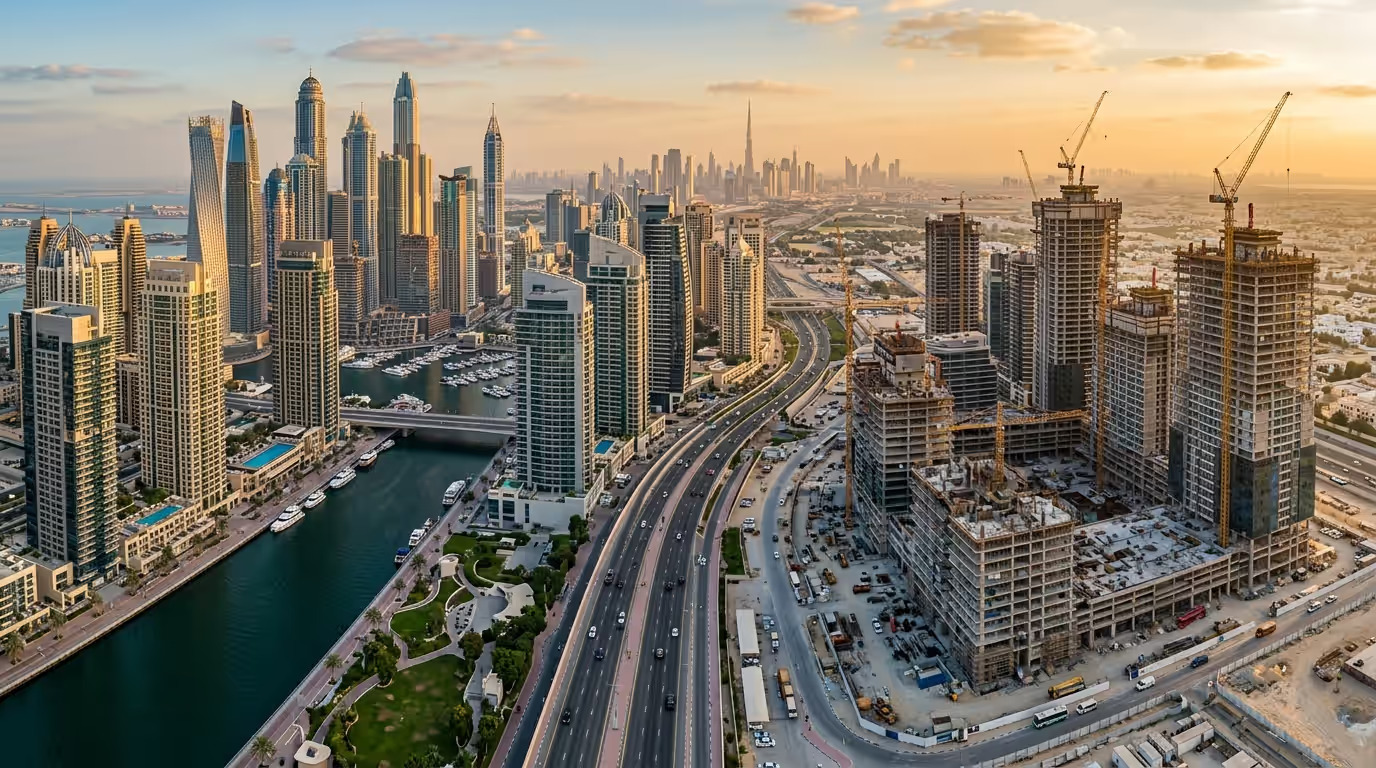
Dubai offers two distinct routes to build a property portfolio: buying off-plan (under construction) or buying ready (completed) units. Both can be excellent investments, but they serve different goals, risk tolerances, and cash-flow needs.
This guide breaks down the key differences—from pricing, fees, and financing to timelines, rental prospects, and exit strategies—so you can decide which approach aligns with your objectives.
Off-Plan vs Ready: What Each Really Means
Off-plan purchases are properties sold by developers before or during construction. You secure at today's price and pay in stages via a payment plan, with handover on completion. Ready properties are completed and can be occupied or rented immediately; they transact on the secondary market (or occasionally as brand-new inventory directly from a developer).
Typical characteristics:
- Off-plan: staged payments, lower entry ticket vs comparable future-ready unit, higher price appreciation potential but construction/delivery risk.
- Ready: full price (or mortgage) at transfer, immediate rental income, clearer inspection of condition and community maturity.
Regulatory backdrop: Dubai’s real estate is highly regulated. For both paths, buyers pay a 4% Dubai Land Department (DLD) registration/transfer fee. Off-plan sales are registered (Oqood) with DLD; ready sales transfer title at the DLD Trustee Office. Developers must escrow buyer funds for off-plan projects and construction milestones are overseen by authorities.
Costs and Fees: What You Actually Pay
Both routes involve core government and transactional costs. Percentages are typical ranges and may vary by project and service provider.
- DLD fee: 4% of the purchase price (payable on Oqood registration for off-plan; on title transfer for ready).
- Agency commission: commonly around 2% for ready; off-plan can range from 0% to ~2% depending on project and promotions.
- Trustee/registration/admin fees: standard trustee office fees apply to ready transfers; off-plan has Oqood/registration and admin fees. Expect a few thousand dirhams in admin/trustee charges in either case (plus 5% VAT on professional services).
- Developer fees: NOC fee for ready resales; off-plan handover/connection fees (e.g., utilities/chiller setup) and snagging.
- Service charges: annual community service charges per sq ft vary widely by community and asset class.
Timing of major payments typically differs:
- Off-plan: pay booking + 4% DLD registration early, then construction-linked installments; final installment at handover.
- Ready: pay deposit on signing, then settle remaining price, 4% DLD, trustee, NOC, and commission at transfer, usually within 30–60 days.
Financing and Leverage Considerations
Mortgages are widely available in Dubai, with loan-to-value (LTV) limits governed by the UAE Central Bank. As a general orientation (actual eligibility varies by buyer profile, bank policy, and property):
- Ready properties: end-user/first-home expatriate buyers often see up to around 80% LTV for properties up to a certain value threshold; lower LTVs apply above that threshold and for second homes or investors. UAE nationals typically have higher caps.
- Off-plan: banks may offer limited construction-stage financing on select developer-approved projects, often with lower LTVs (commonly up to around 50%). Many investors self-fund installments, then refinance at handover as a ready property mortgage.
Practical tips:
- Get an AIP (approval in principle) before committing to a timeline-sensitive deal.
- Align payment plans with liquidity—off-plan post-handover plans can smooth cash flow but may carry a price premium.
- Interest rates, early settlement fees, and bank valuation outcomes can materially affect ROI—stress-test your model.
- Factor bank valuation risk; it may differ from your agreed price.
- Check if your project is on the bank’s approved list for off-plan financing.
- Ensure life insurance and property insurance costs are included in your affordability.
ROI: Rental Income vs Capital Appreciation
Ready properties can generate income immediately. In established communities, gross rental yields for apartments often fall in the ~5–8% range, and villas/townhouses in the ~4–6% range, depending on location, quality, and management. Net yields depend on service charges, agency leasing fees, and vacancy.
Off-plan investments usually aim for price growth from launch to handover and beyond. Early phases in strong locations can see meaningful appreciation by completion—especially where infrastructure and supply-demand dynamics are favorable. However, timelines and market cycles introduce uncertainty; appreciation is indicative, not guaranteed.
Illustrative, not guaranteed: buying off-plan at an early launch price with a competitive payment plan may allow you to lock in perceived value and resell (assignment) before handover if the developer permits and once a minimum percentage is paid. Policies vary by developer, and assignment fees/NOCs apply.
Short-term letting: Ready apartments in tourist zones can target higher gross income, subject to DTCM permits and operator costs; suitability depends on building rules and licensing.
Risk Profile and How to Mitigate It
Key risks differ by strategy:
- Off-plan risks: construction delays, design/spec modifications, market softening before completion, lower-than-expected bank valuation at handover.
- Ready risks: hidden unit defects, inflated service charges, community oversupply, tenant default or vacancy.
Mitigation checklist:
- Verify developer track record, escrow compliance, and previous handover punctuality.
- Review the SPA carefully (completion dates, delay clauses, finishing schedules, snagging/rectification).
- Commission independent snagging for ready and at off-plan handover.
- Compare service charges and sinking fund provisions across peer buildings.
- Keep a liquidity buffer for 6–12 months of mortgage and service charges.
Process and Timeline: What to Expect
Ready purchase (secondary market):
- Agree price and sign Form F/contract, pay a reservation/deposit.
- Arrange mortgage (if any), complete valuation.
- Obtain developer NOC; settle service charge clearance.
- Transfer at DLD Trustee Office: pay balance, 4% DLD transfer, trustee/admin fees, and commission; title deed is issued.
Off-plan purchase:
- Select unit and payment plan; sign the SPA.
- Pay booking and 4% DLD registration (Oqood) plus applicable admin fees.
- Make construction-linked installments; monitor progress via RERA updates.
- Handover: snag the unit, settle final installment, pay connection/handover fees. For first transfer from developer, registration is already with DLD via Oqood; title is issued in your name at completion.
Developer warranty: New builds in Dubai generally carry a one-year defect liability period for unit finishes and a longer structural warranty (commonly up to 10 years) from completion. Check your SPA for exact terms.
Legal, Visa, and Resale Nuances
Ownership: Freehold areas allow foreign ownership. Confirm the project is in a designated freehold zone and that the developer is licensed and escrow-backed.
Golden Visa: Property investors may qualify for a 10-year UAE Golden Visa with property investment of at least AED 2 million. For mortgaged or off-plan assets, authorities typically require a minimum paid-in equity level and that the project/developer is approved; criteria can evolve, so confirm current rules with DLD or ICP before committing.
Resales:
- Ready: standard secondary sale with NOC, service charge clearance, and DLD transfer.
- Off-plan: assignment before handover depends on developer policy, minimum % paid (often 30–40%+), and applicable assignment/NOC fees. Some payment plans restrict resale until specific milestones.
Who Should Choose What?
Choose off-plan if you:
- Prioritise lower entry prices and staged payments.
- Aim for medium-term appreciation and can tolerate construction timelines.
- Don’t need immediate rental income and can hold through cycles.
Choose ready if you:
- Want instant occupancy or rental income.
- Prefer full visibility on the building, community, and service charges.
- Need conventional mortgage leverage at market LTVs now.
Balanced approach:
- Build a barbell portfolio: a cash-flowing ready asset plus a growth-focused off-plan unit.
- Ladder off-plan entries across different handover years to diversify timing risk.
Head-to-Head Comparison
| Factor | Off-Plan | Ready |
|---|---|---|
| Entry Price | Typically lower vs future-ready equivalent | Market price today |
| Cash Flow | None until completion | Immediate rental potential |
| Payment Structure | Construction-linked installments; some post-handover plans | Lump sum at transfer; mortgage-driven |
| DLD Fee | 4% on Oqood registration at sale | 4% on title transfer |
| Agency Commission | 0–~2% typical | ~2% typical |
| Financing (indicative) | More limited LTVs during build; refinance at handover | Wider mortgage options and higher LTVs (subject to eligibility) |
| Risk | Construction and timeline risk | Unit/tenant and market yield risk |
| Exit Before Handover | Possible if developer allows, with NOC/fees | Standard secondary sale |
| Warranty | New-build defect and structural warranties at handover | Varies by building age; limited if older |
A Simple, Illustrative ROI Lens
This is illustrative only—not a forecast. Suppose you buy an off-plan apartment with a competitive launch price and a 60/40 payment plan. If market prices rise by handover and you’ve paid 60%, your equity multiple could expand meaningfully—provided valuations and demand hold. Conversely, if market softens or delays occur, your returns compress and holding costs rise.
With a ready apartment in an established area, you might target a gross yield in the mid-single digits and optimise net returns via efficient property management, competitive mortgage rates, and vacancy control. The upside is steadier cash flow; the trade-off is typically lower headline appreciation versus a well-timed off-plan entry.
Common Mistakes to Avoid
- Ignoring the 4% DLD fee. Underestimating upfront costs skews ROI and liquidity planning.
- Overleveraging on optimistic rents. Bank valuations and real rents can be lower than asking—stress-test your numbers.
- Skipping developer due diligence. Track record, escrow compliance, and delivery history matter for off-plan.
- Not checking service charges. High per‑sq‑ft fees can erode net yields in both off-plan and ready buildings.
- Assuming you can flip any off-plan. Resale often requires minimum % paid, NOCs, and may incur assignment fees.
Conclusion
There is no universal “smarter” choice—only the right fit for your goals. If you want staged capital calls and believe in a project’s growth trajectory, off-plan can be compelling. If you prioritise immediate income, clarity, and mainstream financing, a quality ready asset in a strong community is hard to beat. Many successful Dubai investors blend both to balance growth and cash flow. Speak to Binayah Properties for curated project selection, yield modelling, and end-to-end execution.