Dubai hotel market report: tourism rebound 2026
On 15 September 2026 Dubai hotel market showed renewed strength as the city’s hotel sector reported sustained performance growth in official Dubai Department of Economy and Tourism data.
The Dubai Department of Economy and Tourism released fresh findings on 15 September 2026 confirming that the hotel sector is delivering sustained performance growth driven by stronger visitor flows and rising demand for short-stay accommodation. This official framing matters because it moves the narrative from a temporary bounce back to a broader recovery that touches room revenue, operational occupancy and investor confidence across hospitality-linked assets.
For owners and investors the key point is how that improved hotel performance feeds other parts of the property market. Higher hotel demand often raises short-stay rates, lifts F&B and retail footfall inside mixed-use developments, and can encourage owners to retain or refurbish inventory rather than discounting. The rest of this report unpacks those links and outlines the near-term risks to watch.
What does the latest tourism rebound mean for Dubai hotel market?
What does the latest tourism rebound mean for Dubai hotel market? Key Data
Report date
15 September 2026
Source
Dubai Department of Economy and Tourism
Sector
Hotel
Trend
Sustained performance growth
The tourism rebound means stronger demand and clearer revenue trajectories for Dubai hotels, according to Dubai Department of Economy and Tourism data published on 15 September 2026.
That official report describes the hotel sector as delivering sustained performance growth, signalling that visitor demand is not just a short spike but is supporting steady operational improvement across Dubai’s hotel stock. For owners this reduces the immediate pressure to cut rates and creates a more predictable environment for revenue management and short-term capital expenditure planning.
The nuance is timing and depth: stronger headline performance does not eliminate market pockets where supply is heavy or where older hotels need repositioning. Investors should expect a differentiated market by segment and community, with premium locations recovering fastest while peripheral or oversupplied areas may lag despite citywide tourism gains.
How does hotel performance feed the wider Dubai real estate market?
Stronger hotel performance supports higher short-stay rates, greater footfall in retail and restaurants, and renewed investor confidence in hospitality-linked properties, the official Dubai Department of Economy and Tourism data indicates.
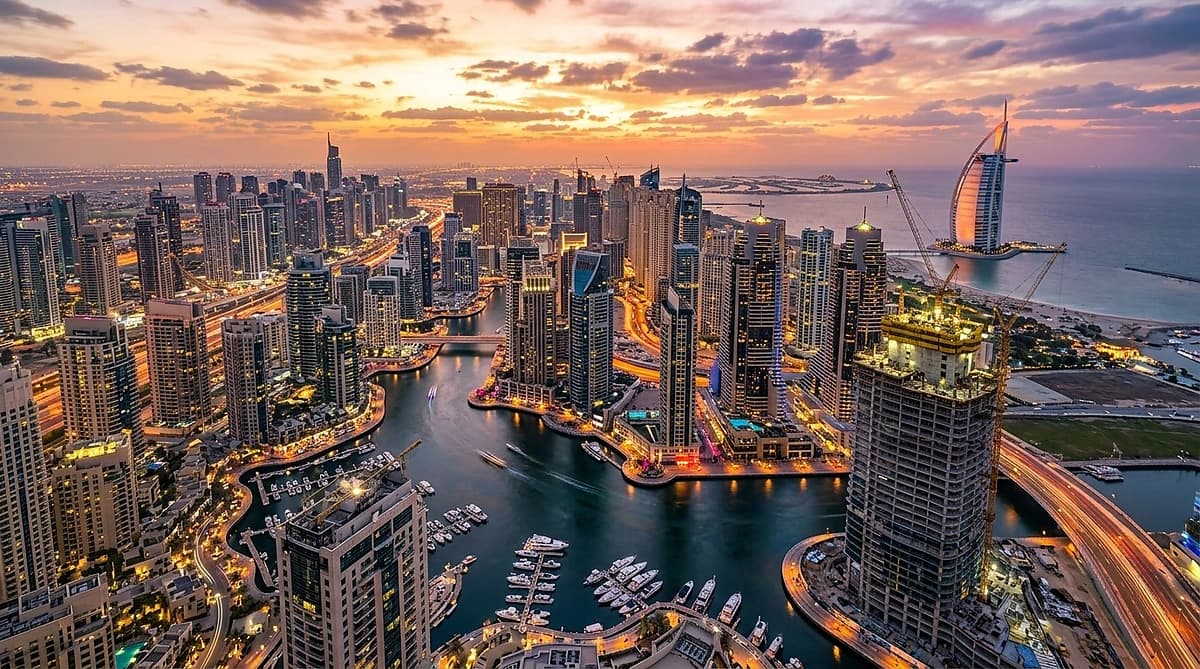
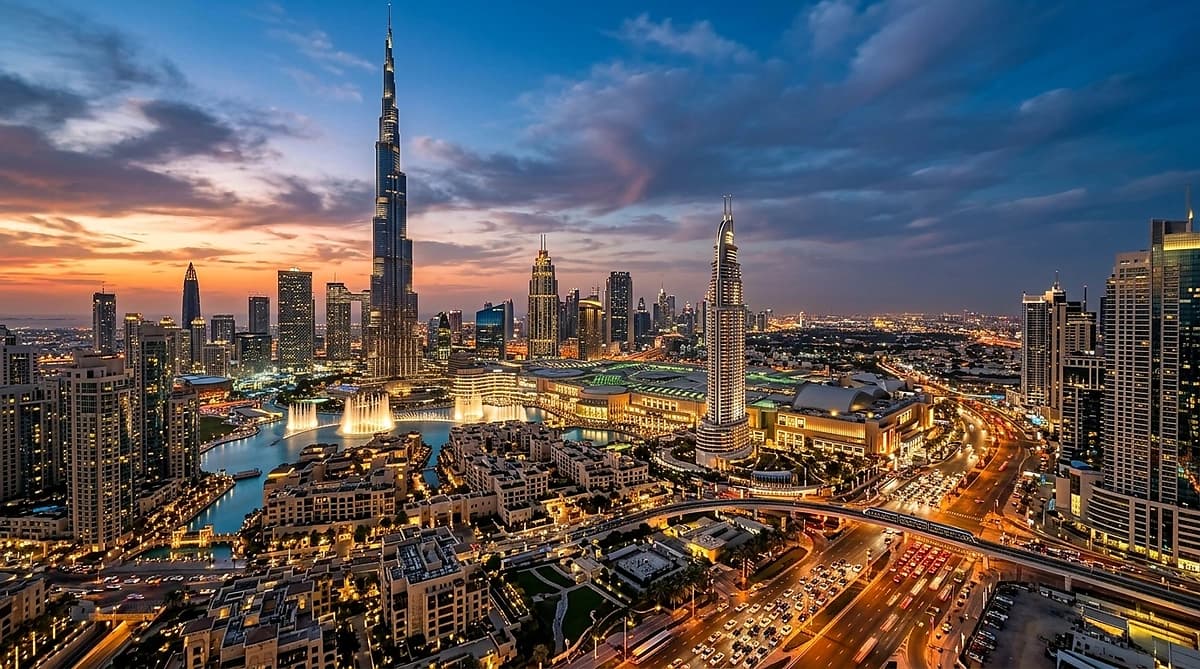
When hotels perform well they increase visitation to mixed-use developments and raise demand for serviced apartments and short-term rentals, which in turn can lift yields for nearby residential landlords and boost retail leasing interest. This effect is particularly visible in areas with high tourist concentration such as Downtown, Dubai Marina and Palm Jumeirah, where hotel guests provide consistent daily spending and create cross-demand for adjacent residential and retail assets.
There is a balance to monitor: improved hotel results can encourage more hotel development or conversion of residential stock into short-stay units, which could moderate rental upside if supply grows faster than visitor demand. Planning approvals, pipeline timing and operator strategies will determine whether the hospitality rebound becomes a structural support for wider real estate values or a more short-lived uplift.
| Impact area | How the hotel sector changed | Why it matters |
|---|---|---|
| Visitor demand | Increased and more consistent | Raises short-stay revenues and local spending |
| Serviced apartments | Higher occupancy pressure | Boosts rental interest and operator economics |
| Retail and F&B | Stronger footfall | Improves tenant performance and leasing appetite |
| Investor sentiment | More confident | Supports pricing for hospitality-linked assets |
"The latest data confirms the tourism rebound is translating into sustained hotel performance growth across Dubai."
, Dubai Department of Economy and Tourism
What should investors watch next in the Dubai hotel market?
Investors should watch occupancy stability, operator pricing, and the pace of new hotel supply as the next indicators of whether the rebound deepens or softens.
Occupancy trends and average room rate strategies from major operators will show if demand is broad-based or event-driven. Watch whether hotel revenue improvement spreads to serviced apartments and short-term lease listings, and monitor approvals and construction starts that could add supply in the next 12 to 36 months. Changes in visa rules, tourism promotion campaigns and major events will also affect visitor composition and length of stay, which matters for hotel economics and for nearby residential rental demand.
Risks include a clustered increase in new hotel openings that coincides with only moderate growth in visitors, and a shift in guest mix toward lower-spend segments that lifts occupancy but keeps revenue per available room under pressure. For investors the sensible approach is to prioritise hotels and hospitality-linked real estate in proven tourist hubs and to stress-test cashflow assumptions against slower demand scenarios.
- Monitor occupancy and average room rate trends
- Track approvals and construction for new hotels
- Assess spillover impact on serviced apartments
- Follow major events and tourism promotions
What is the short-term outlook for the Dubai market after the tourism rebound?
What is the short-term outlook for the Dubai market after the tourism rebound? Key Data
Near-term outlook
Cautiously positive
Confirmed by
Dubai Department of Economy and Tourism
Primary driver
Visitor demand
Key risk
New supply growth
The short-term outlook is cautiously positive: the official 15 September 2026 report points to sustained hotel performance growth, which supports a near-term recovery in hospitality-related real estate activity.
Expect incremental improvement in revenue management and tenant performance across mixed-use developments as hotel guests return more regularly and retail sales linked to tourists firm up. That said, outcomes will vary by neighbourhood and by property quality; prime locations with strong operator representation are likely to see the clearest benefits while non-prime areas may experience slower or uneven recovery.
Investors should prepare for a phased recovery rather than an immediate broad-based rise in values, keeping focus on cashflow resilience and operator contracts. Monitoring official tourism releases and operator earnings will provide the earliest signals that the sustained performance described by Dubai’s authorities is continuing.
The Dubai Department of Economy and Tourism data published on 15 September 2026 characterises the hotel sector as delivering sustained performance growth, supporting a cautiously positive short-term outlook. That sustained performance strengthens hospitality-linked cashflows and benefits prime-location residential and retail assets, while the primary risks remain concentrated new supply and uneven recovery across neighbourhoods.
Binayah Editorial
Property Market Analyst
Our editorial team researches Dubai's real estate market, tracking DLD data, developer launches, and investment trends to keep buyers and investors informed.
Ready to Invest in Dubai?
Speak with our analysts about the best opportunities in today's market, free consultation.